Action to Implement Management that is Conscious of Cost of Capital and Stock Price
Cost of Capital and Return on Capital - Current Status and Issues
Analysis of Current Situation
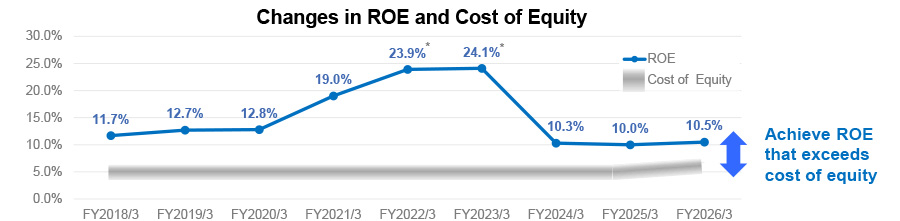
- Current cost of equity is approximately 7-8%, based on CAPM and other analyses, reflecting the rising interest rate environment
- Since listing, ROE has consistently exceeded cost of equity
- ROE reached a record high from FY2021/3 to FY2023/3 amid strong earnings growth during COVID-19
- Since FY2024/3, growth investments have expanded, and improvements in capital profitability by business segment are still underway
- Rising interest rates potentially becoming a medium- to long-term trend, upward pressure on the cost of equity is expected to continue
Recognition of the Issues
- Continued improvement in ROE is required while controlling the cost of equity
-
*Net income attributable to owners of the parent for FY2022/3 and FY2023/3 includes extraordinary gains from the sale of shares of LOGISTEED, Ltd. (the same hereinafter)
Market Evaluation - Current Status and Issues
Analysis of Current Situation
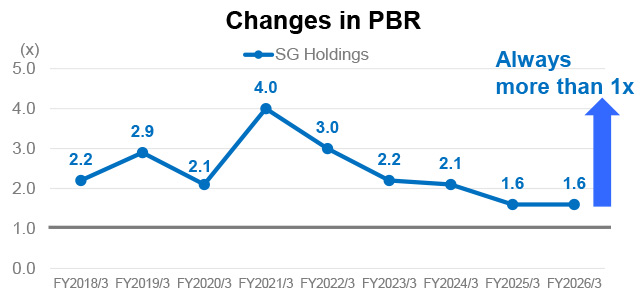
- Since listing, PBR has consistently remained above 1x, supported by a high level of ROE compared with other companies in the transportation sector
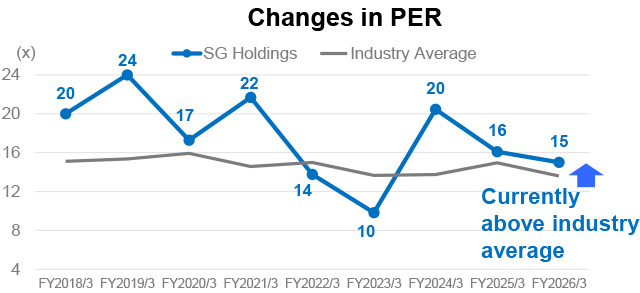
- Current PER is approximately 15x, roughly in line with the industry average of approximately 13x to 16x (TSE Prime Market and land transportation sector)
Recognition of the Issues
- Sustained achievement of PBR above 1x is required through enhanced disclosure on Total Logistics sophistication and dialogue with the capital markets
- The current PER does not sufficiently reflect growth potential, highlighting the need for improvement efforts
-
*The Company conducted a 2-for-1 stock split on November 1, 2020. The PBR and PER figures have been calculated on the assumption that the stock split had been effective from the beginning of FY2018/3
Initiatives to Achieve Management that is Conscious of Cost of Capital and Stock Price - Planning and Disclosure
Target Level
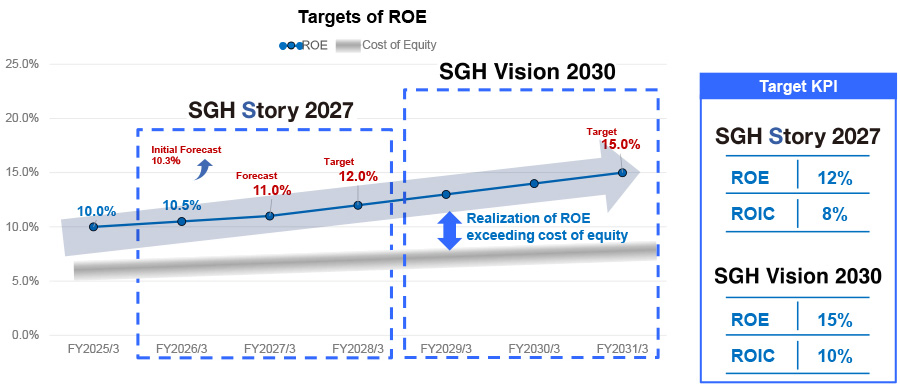
- Achievement of ROE of 15% by FY2030 is targeted through improving the profitability across businesses and enhancing shareholder returns
Initiatives to Achieve Management that is Conscious of Cost of Capital and Stock Price - Specific Measures
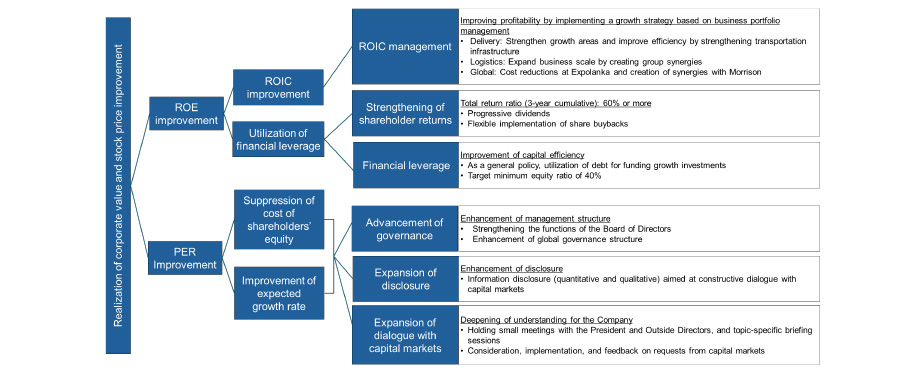
Logic Tree for Improving Corporate Value and Stock Price
ROE Improvement (1)
- ROIC Management: Improving Profitability by Executing Growth Strategies Based on the Business Portfolio
-
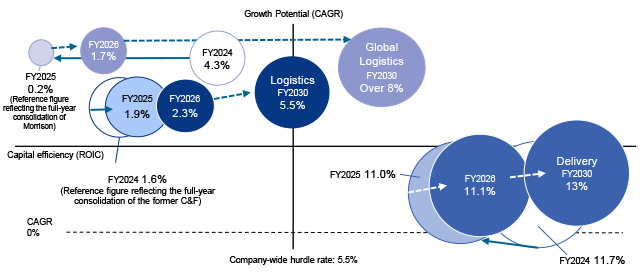
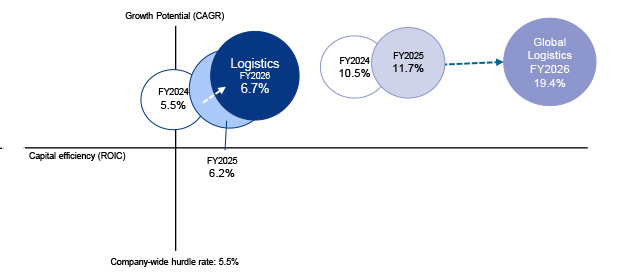
The company-wide hurdle rate is set at 5.5%, based on WACC and other factors. ROIC remains high in the Delivery Business.
ROIC in the Logistics and Global Logistics Businesses temporarily declined due to an increase in goodwill associated with M&A, but profit contributions from acquired businesses have begun to materialize
Delivery Business
- From FY2024 onward, ROIC declined year on year due to factors including increased invested capital for the construction of largescale transfer centers, but generally remained at around 11%
- The phase of large-scale growth investment has run its course.Going forward, investment will focus on labor-saving and efficiency-enhancing initiatives, including digital transformation, to ensure the steady recovery of invested capital. Review the asset holding policy and focus on improving profitability through investment returns
Logistics Business
- From FY2024 onward, ROIC declined due to the increase in goodwill resulting from the acquisition of the former Chilled & Frozen Logistics Holdings (C&F)* (ROIC improved when excluding the impact of goodwill)
- In FY2026, the low temperature logistics business will improve profitability through more advanced profitability management while strengthening its business foundations, including the launch of new facilities. Aim to achieve the FY2030 target of 5.5% through investments focused on profitability
Global Logistics Business
- In FY2025, ROIC declined due to the increase in goodwill resulting from the acquisition of Morrison and a decline in profit of Expolanka. However, ROIC improved when excluding the impact of goodwill, reflecting Morrison’s inclusion in the Group
- In FY2026, synergies between Expolanka and Morrison will be promoted. ROIC is expected to improve by concentrating resources on the freight forwarding business and pursuing organizational reforms to strengthen profit-generating capabilities
ROIC by Segment: Results and Outlook
ROIC by Segment (Excluding the Impact of Goodwill, etc.)*
-
*The Delivery Business is excluded because the impact of goodwill is minimal
-
*Absorption-type merger with Meito Transportation Co., Ltd. as the surviving company, effective April 1, 2025.
-
*ROIC by segment = NOPAT by segment / invested capital by segment. NOPAT by segment is calculated by adjusting operating income by segment for the effective tax rate, while invested capital by segment is calculated as the average working capital plus fixed assets for each segment during the fiscal year. ROIC by segment (excluding goodwill, etc.) is calculated by excluding goodwill amortization expense from NOPAT by segment and goodwill, etc. from invested capital by segment.
ROE Improvement (2)
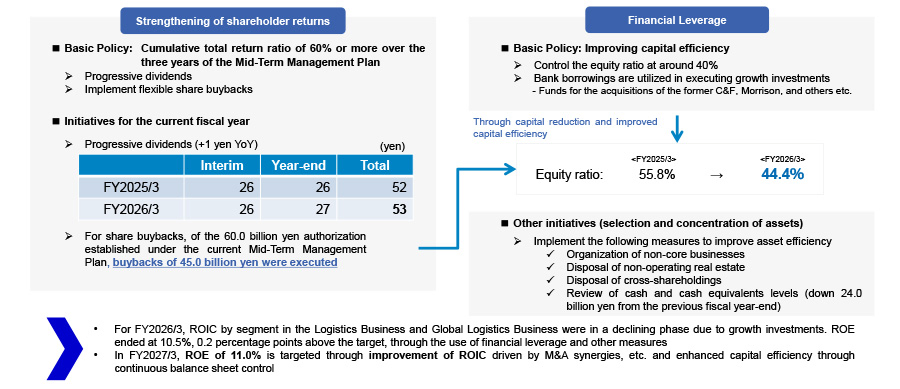
- Utilization of Financial Leverage
- In FY2026/3, ROE ended up at 10.5%, exceeding the initial forecast, through balance sheet management measures such as the use of financial leverage for growth investments
Improvement of PER
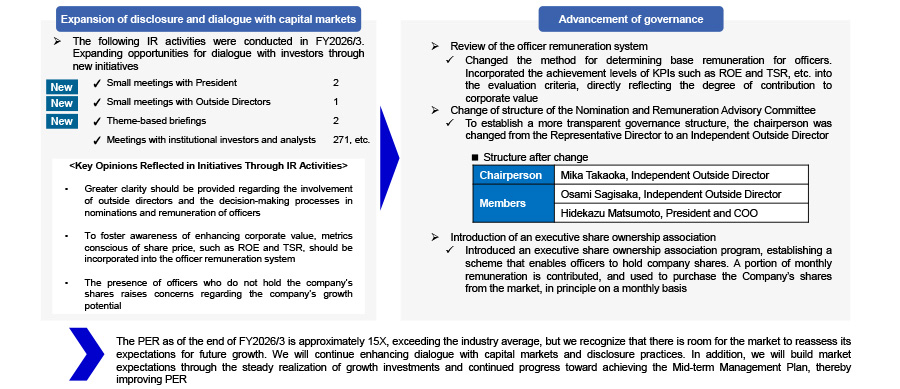
- Suppression of cost of shareholders’ equity and improvement of expected growth rate
- Implementing various initiatives to enhance governance through dialogue with shareholders and investors
- Action to implement management that is conscious of cost of capital and stock price - (July, 2026) (1.4MB)
